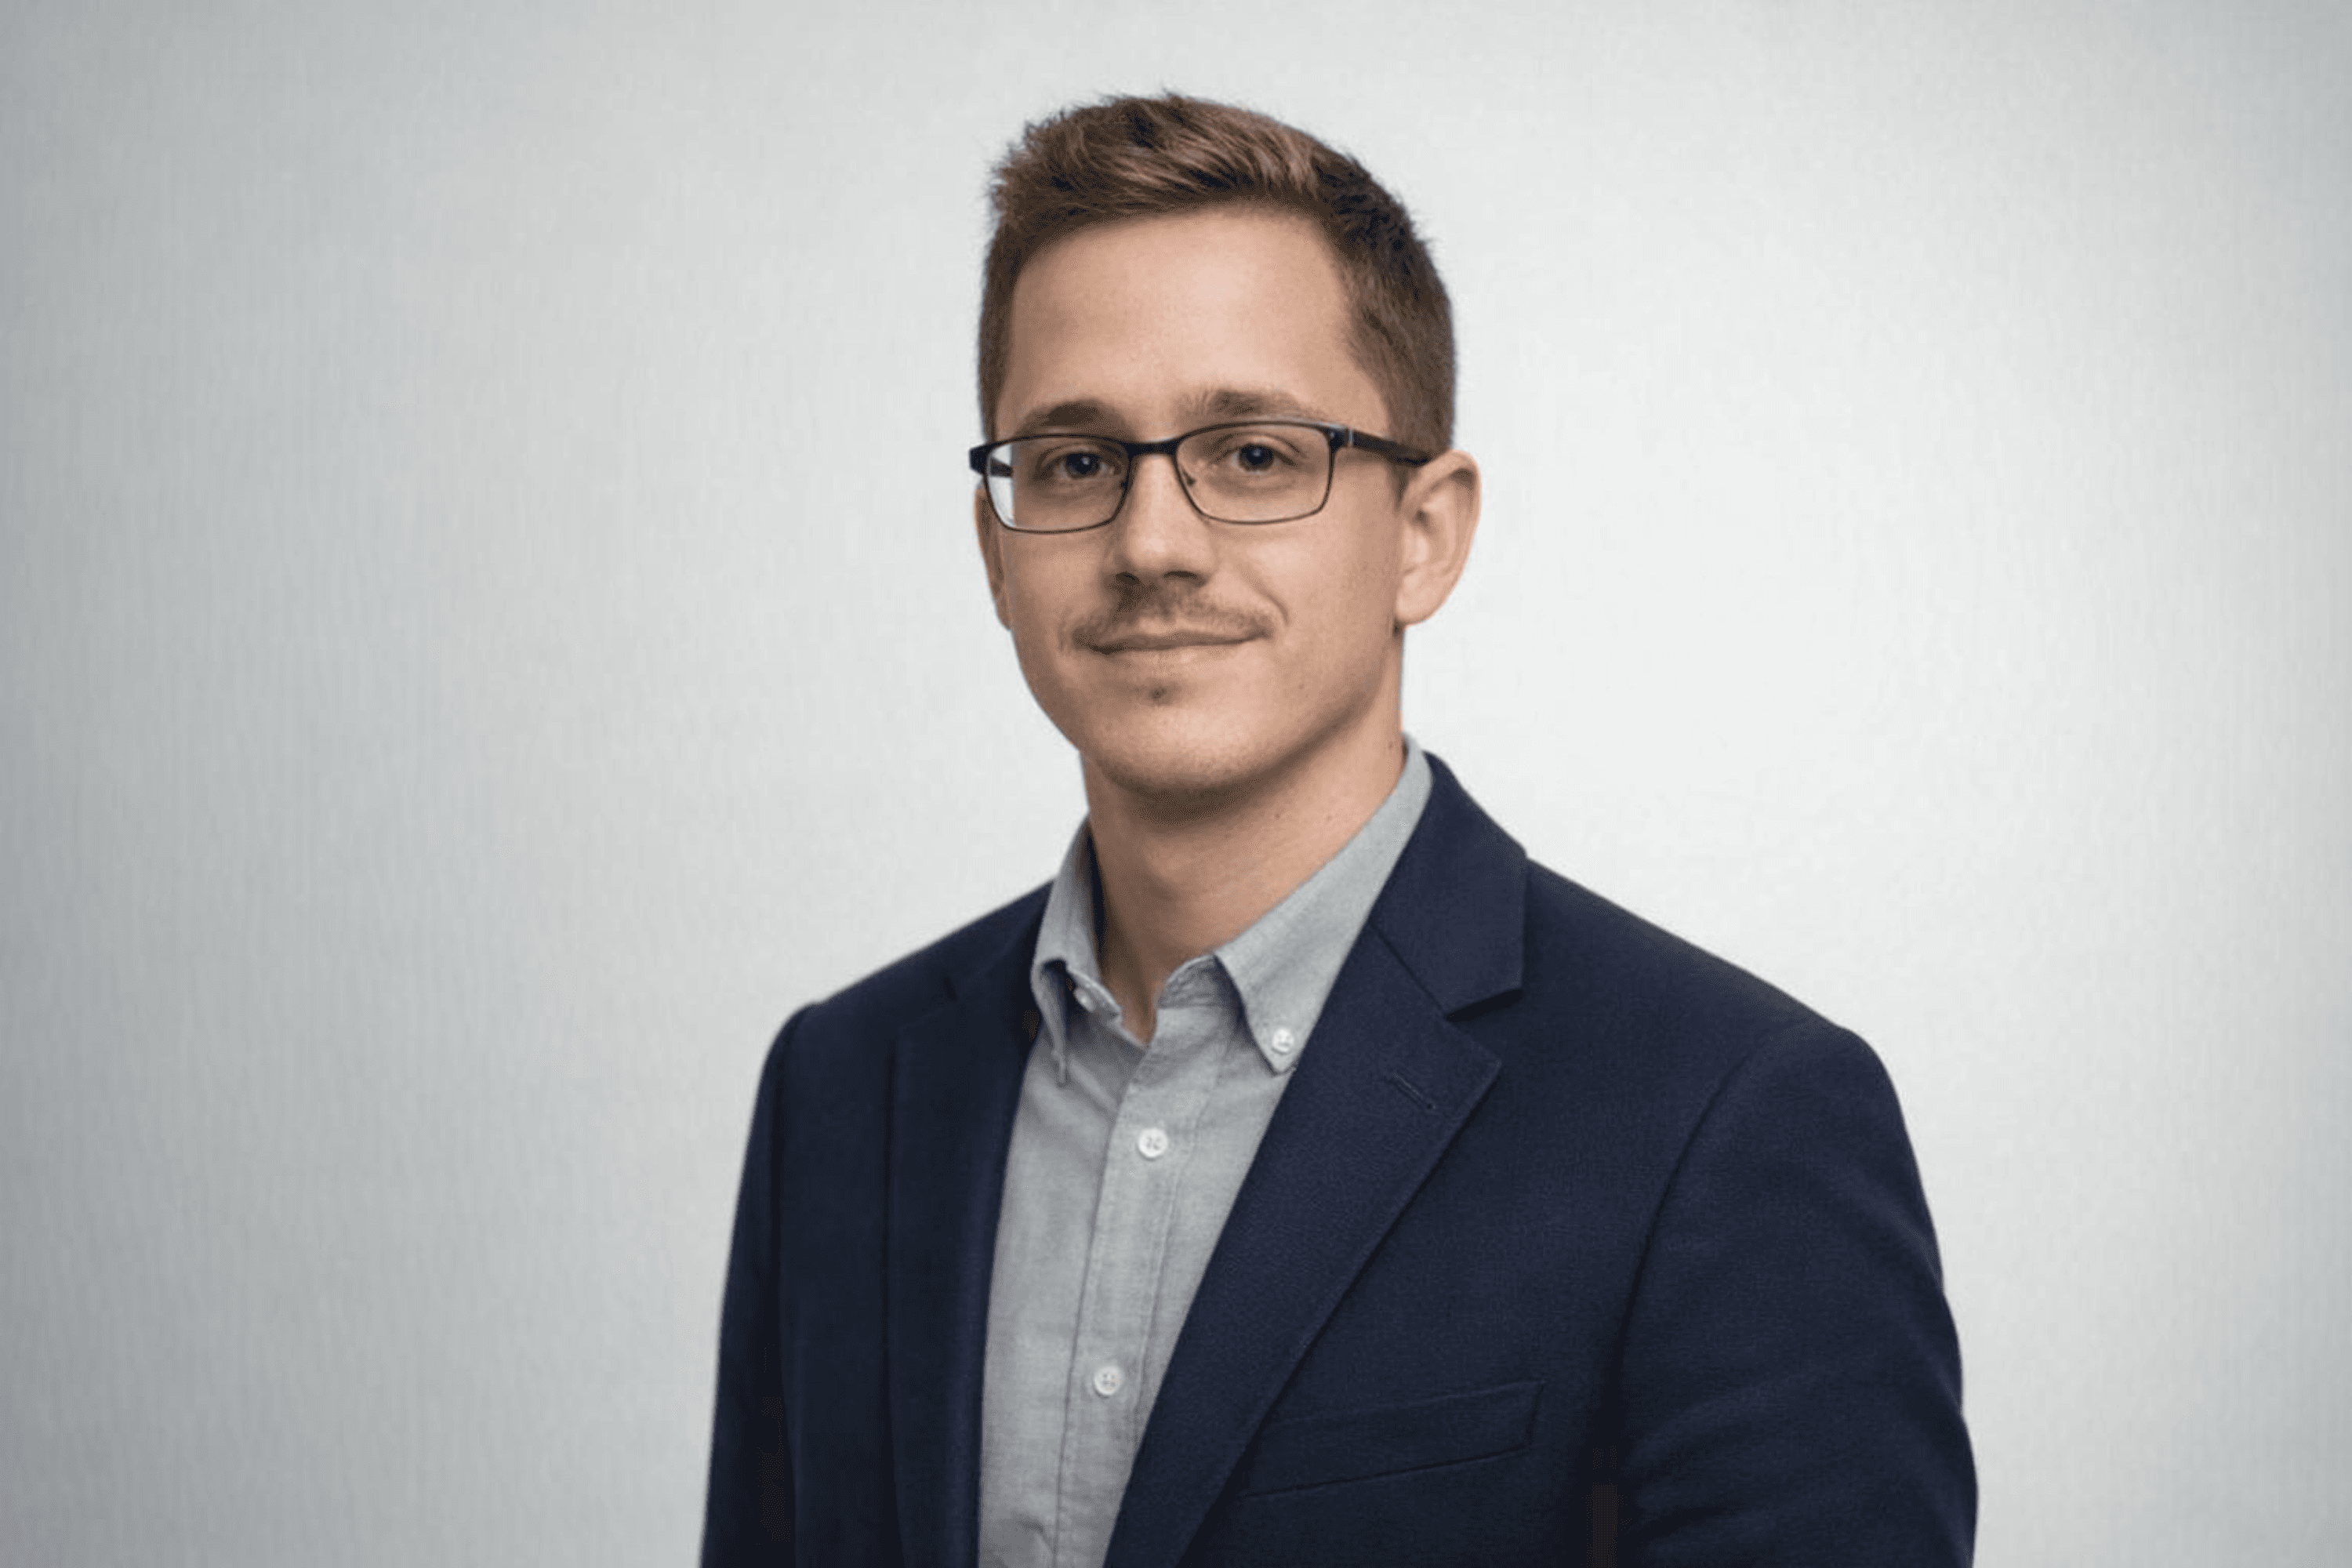
Hi, I'm Tom, Springfield Central's mortgage broker. Not owned by any bank.
I help families and professionals navigate home loans with calm, clear guidance. The goal isn't just approval. It's a structure you understand and a plan that holds up over time.
- Diploma in Finance (Kaplan)
- FBAA Member No. M-361617
- AFCA Member No. 119278
- Credit Representative No. 575209 (ACL 486112)
Why I started Kookaburra Finance
I'm not a career banker, and that's the whole point. For nearly two decades I've led complex, high-stakes delivery across enterprise software, telecommunications, aviation and energy. The work never really changed shape: take something complicated and make it work for the people inside it.
A home loan is exactly that kind of system. It's the biggest contract most people ever sign, and it's usually explained in a way that suits the lender rather than the borrower. I started Kookaburra Finance to bring the same rigour and plain English I've built my career on to the one deal that matters most to a family.
It's also why I build the tools on this site myself. The AI rate check that reads your loan statement and grades it isn't an off-the-shelf widget. I engineered it, because I would rather show you the numbers than ask you to trust a sales pitch.
Backed by a Diploma in Finance and FBAA accreditation, and based right here in Springfield Central, the promise is simple. Honest options, 60+ lenders compared, and a broker who is still around long after settlement.
How we work
This is how we approach every client relationship, from the first call to years after settlement.
Best Interests Duty (legally and morally)
We're legally required to act in your best interest. But that's the floor, not the ceiling. Every recommendation we make is genuinely the right one for you.
Plain English, always
Mortgages aren't complicated. They're just made to sound that way. We explain every option clearly, so you make confident decisions, not guesses.
We don't disappear at settlement
Most brokers vanish once your loan settles. We do annual rate reviews, check in when RBA moves rates, and are always here when you need us.
Local knowledge that matters
Springfield Central is where we live and work. We know the local market, the builders, the agents, and we use that knowledge for your benefit.
Not owned by any bank. Here's what that means for you.
Many broking services are bank-owned subsidiaries. We are not. Here's what that means in practice.
No bank ownership
We are not owned by, operated by, or financially controlled by any bank or lender. Many broker services are bank-owned subsidiaries. We are not. Our panel choices are made entirely on merit.
No product quotas
Some brokers are pressured to place a minimum volume of loans with certain lenders. We have none. Every lender recommendation is made purely because it's the best fit for your situation.
Best Interests Duty
Under ASIC legislation (effective Jan 2021), we are legally required to prioritise your interests over our own. This duty applies to mortgage brokers, not bank staff selling their own products.
Mortgage broker vs bank staff
The difference isn't subtle. It fundamentally changes what's possible for you.
| Feature | Kookaburra Finance | Bank mortgage specialist |
|---|---|---|
| Lenders available | 60+ lenders | 1 (their own) |
| Best Interests Duty | ✓ Legally required | ✗ Not applicable |
| Cost to you | None | None |
| Can compare rates | ✓ Real-time comparison | ✗ Only their own |
| If declined by one lender | We try others | You're told no |
| Specialist loan types | ✓ Self-employed, SMSF, low doc | Limited options |
| Lender affiliation | ✓ None. Not owned by any lender | ✗ Employed by lender |
| Application management | ✓ We handle everything | You manage it |
How we protect your interests
Your interests are protected through process, not just intention.
Every loan recommendation comes with written documentation of why we chose it: what alternatives were considered, why this lender and product was selected, and how it serves your goals.
Our Credit Guide (available before you engage us) discloses the commission structure. There are no hidden fees, no trail commissions that incentivise us to keep you in a bad loan, and no referral fees from lenders.
We regularly assess our lender panel against market rates and service quality. Lenders who aren't competitive get deprioritised, regardless of their commission structure.
There's no engagement fee and no obligation. If you're not satisfied with our recommendation or want a second opinion, you are free to walk away at no cost.
Common questions about using a mortgage broker
What being broker-owned means for you, and how the rules protect you.
What does it mean that Kookaburra Finance is not bank-owned?
How does Kookaburra Finance make money if the service costs nothing?
Are you required to recommend the best loan for me?
What's the difference between a mortgage broker and a bank's mortgage specialist?
How do I know you won't steer me toward high-commission lenders?
Ready to work with a broker who actually cares?
Book a free 15-minute call. No jargon, no pressure: just honest advice about what's possible for you.